UK & US Diaspora vs. Lagos Property Market in 2026: The Real Numbers on Returns, Risks, and What ₦50 Million Gets You
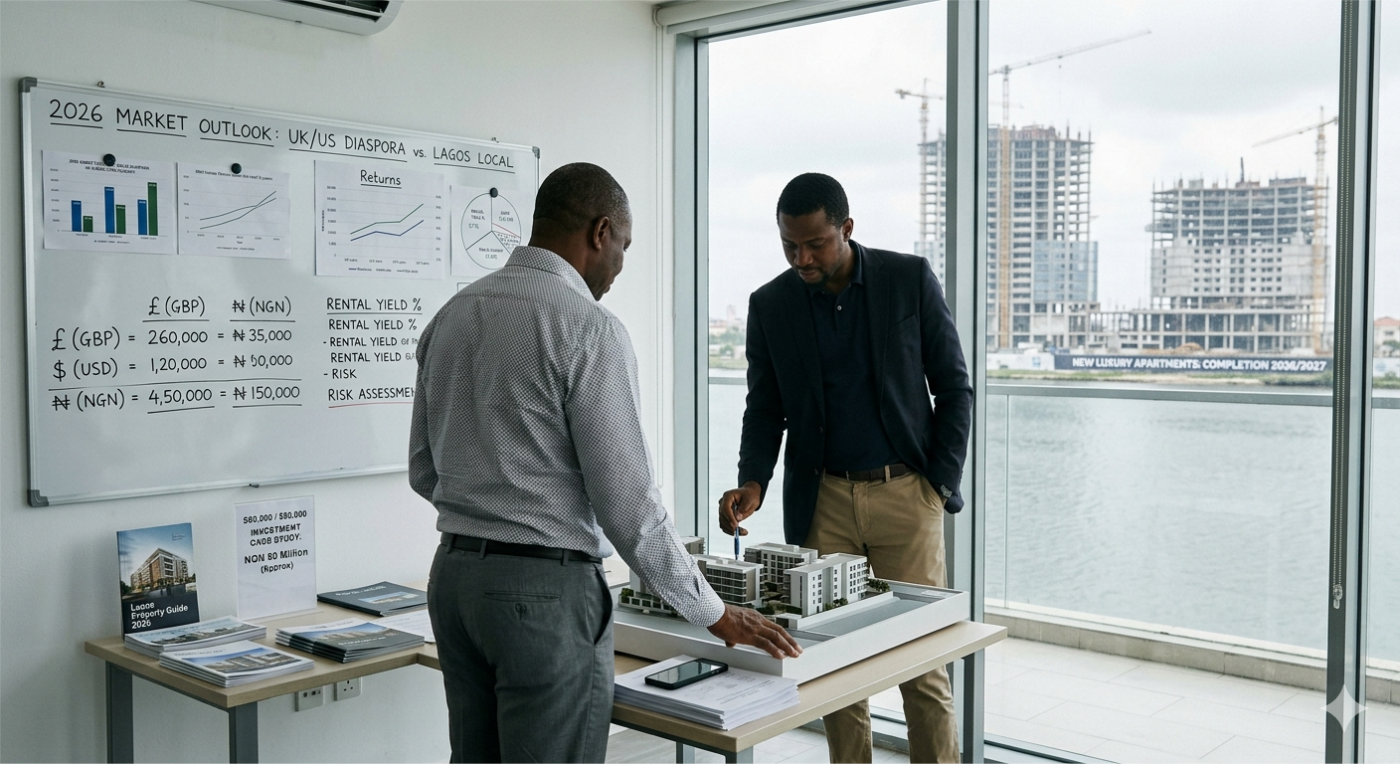
For Nigerians in the UK, US, and Canada, the question of whether to invest in Lagos property is fundamentally a question of comparative returns. Is a Lagos property in the ₦50M–₦100M range a better investment than a UK buy-to-let or a US index fund? The answer in 2026, when you account for currency dynamics, yield differentials, and capital growth trajectories, is more nuanced and more interesting than most commentators acknowledge.
The Currency Dimension: Naira Weakness Is Both Risk and Opportunity
The naira has depreciated sharply since 2023’s FX unification. From approximately ₦470/$1 in early 2023 to roughly ₦1,600/$1 in mid-2026, the naira has lost over 70% of its value against the dollar in three years. For diaspora investors remitting from the UK or US, this means:
– Entry prices in dollar terms are historically low: A Lagos property that cost $85,000 at the old rate now costs approximately $47,000 at the current rate, even after the 20% naira price rise
– Rental income in naira loses value in dollar terms: If you earn ₦5M/year in rent on a ₦75M apartment, your gross dollar yield is approximately 4.2%, not the 7% that naira-denominated calculations suggest
– Capital appreciation in naira may not translate to dollar gains: If a property doubles in naira value over 5 years (from ₦75M to ₦150M) but the naira halves again in value, your dollar return is flat
This is the central tension in Nigerian diaspora property investment: high naira yields and apparent capital growth that may be partially or fully eroded by currency depreciation.
The Structural Counterargument: Why Many Diaspora Investors Still Win
Despite the currency headwind, a meaningful portion of diaspora investors in Lagos real estate have generated genuine positive real returns. The reasons are structural:
- Lagos prime property has a partial dollar peg: Luxury and upper-mid-market properties in Ikoyi, Victoria Island, and Eko Atlantic are effectively priced in dollars or dollar-indexed naira. Rental rates for these properties are often quoted in dollars, meaning dollar-earning landlords are naturally hedged.
- Mid-range properties track naira inflation: For ₦40M–₦120M properties, rents are in naira — but naira rents have historically risen roughly in line with general inflation, which itself tracks currency depreciation. A property bought at ₦60M in 2022 and renting for ₦4M/year then likely rents for ₦7M–₦8M/year in 2026 — a 75–100% rent increase that partially offsets the naira’s depreciation.
- Entry prices below replacement cost: The cost of constructing a modern apartment in Lagos is approximately ₦150,000–₦300,000 per sqm of built area. For many mid-range properties trading below that construction cost, there is a fundamental valuation floor — prices cannot fall below what it costs to build equivalent new stock.
- Emotional and utility value: Many diaspora buyers are not purely maximising financial return. They want somewhere for family, a place to return to, a hedge against “what if.” These are legitimate, non-financial returns that should be factored into any honest analysis.
Comparing ₦75 Million Across Different Investment Options (Mid-2026)
At mid-2026 exchange rates, ₦75M is approximately £35,000–£36,000 or $46,000–$47,000.
- Option A: Lagos mid-range 2-bed apartment (Yaba/Gbagada)
– Annual naira rent: ₦5M–₦6.5M
– Gross naira yield: 6.7–8.7%
– Dollar rent equivalent: ~$3,100–$4,100/year
– Dollar yield on $47,000 entry: 6.6–8.7% gross
– Capital growth (naira): 10–15%/year estimated
– Capital growth (dollar): uncertain, dependent on FX trajectory
– Liquidity: moderate (weeks to months to sell)
– Personal use value: high- Option B: UK buy-to-let (regional city, £35,000 deposit on £150,000 property)
– Gross rental yield on property value: 5–7% (Birmingham, Manchester, Leeds)
– Net yield after costs, tax, management: 2.5–4%
– Capital growth: 3–5%/year in stable markets
– Stamp duty: 5% on £150,000 (second property rates)
– Mortgage available: yes, at 5–6% rates in 2026
– Liquidity: high (weeks to sell)
– Personal use value: low (investment property)- Option C: US S&P 500 index fund ($47,000)
– Historical annual return (10-year): 10–12% in dollar terms
– Tax-efficient via 401k/ISA equivalents
– Fully liquid
– No management overhead
– No personal use value
Honest Assessment: The US index fund wins on risk-adjusted dollar returns for purely financial investors. The Lagos property wins on gross naira yield and personal use value. The UK buy-to-let sits in the middle: better liquidity and regulatory protection, but increasingly compressed net yields after costs and tax.
For diaspora Nigerians who have a reason to hold property in Nigeria: personal use, family needs, long-term return plans, the Lagos mid-range at current dollar prices represents genuine value. For purely financial investors without a personal connection or use case, the currency risk is material and should not be ignored.
Practical Checklist for Diaspora Investors in 2026
Before committing any capital:
✅ Can you afford to lock up the capital for 3–5 years minimum?
✅ Do you have a trusted local representative who will manage the property in your absence?
✅ Have you budgeted for property management fees (5–10% of rent), maintenance (1–2% of value/year), and service charges?
✅ Have you obtained independent legal advice on the title?
✅ Have you stress-tested the investment against a further 30–40% naira depreciation scenario?
✅ Do you have a realistic exit plan: who will you sell to, and in what timeframe?
If the answer to all six is yes, Lagos property in the ₦50M–₦120M band remains a defensible and often compelling investment for diaspora Nigerians in 2026. If any answer is no, address it before committing.